

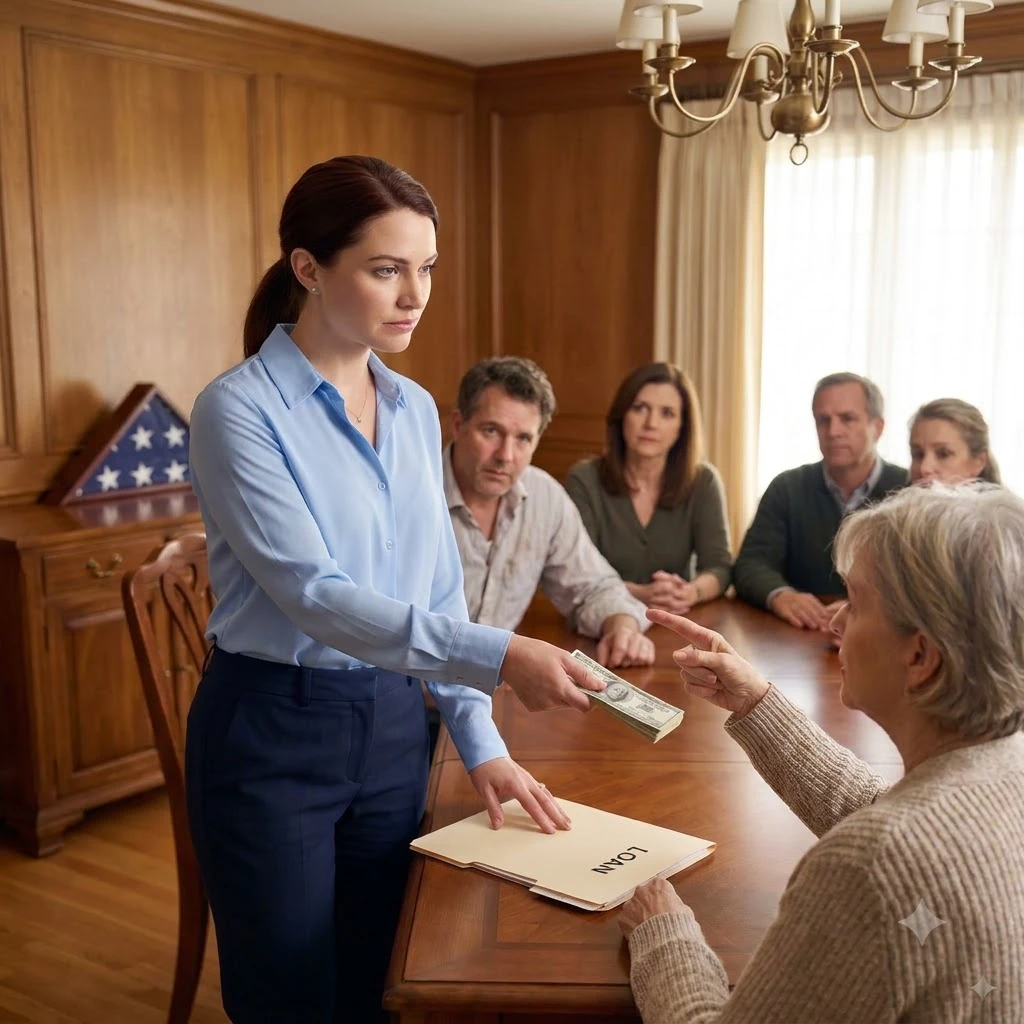
The certified envelope arrived while I was still wearing hospital scrubs, and by the time I reached the second page, **my mother had put a price on every year she had ever loved me.**
Or claimed to.
I stood barefoot in my kitchen with my work bag still hanging from one shoulder, reading the title printed across the first page in bold capital letters.
**COST OF RAISING A FAILURE**
Total amount due:
**$467,214.36.**
I laughed once.
Not because it was funny.
Because sometimes your body makes the wrong sound when your mind cannot process what it is seeing.
Then I turned the page.
Food from birth to eighteen.
Housing.
Utilities.
Clothing.
School supplies.
Medical insurance.
Dental care.
Braces.
Birthday parties.
Christmas presents.
Piano lessons.
Summer camps.
A percentage of family vacations.
The twelve thousand dollars my parents had contributed toward my first two years at Ohio State.
Then came a category called **MATERNAL ADMINISTRATIVE AND EMOTIONAL LABOR**.
Eighty-five thousand dollars.
Apparently, remembering my pediatric appointments had been billable.
So had attending parent-teacher conferences.
So had comforting me after my first breakup.
So had being my mother.
She had even added interest.
At the bottom of page twenty-three, she had handwritten:
**A responsible daughter repays what was invested in her.**
The payment schedule demanded **$60,000 within ten days**.
The rest could be paid monthly over fifteen years.
With interest.
My name is Anna Mercer.
I was thirty-four years old, worked as a diagnostic medical sonographer at a hospital in Pittsburgh, owned a modest two-bedroom townhouse in Bellevue, still had nineteen thousand dollars in student loans, and had spent most of my adult life building stability one careful decision at a time.
According to my mother, Evelyn Mercer, none of that counted.
Because I wasn’t married.
Because I didn’t have children.
Because the initials after my name weren’t M.D.
Because twenty-five years earlier, she had decided what my life should look like, and every choice I made after that became evidence that I had disappointed her.
My older brother Tyler, meanwhile, could do no wrong.
Even while doing almost everything wrong.
Tyler was thirty-nine, handsome in the way men often remain handsome when other people absorb the consequences of their mistakes, and married to Melissa, who had mastered the art of quietly smoothing over whatever wreckage he created.
They had two children, Noah and Ellie.
Tyler owned Mercer Custom Woodworks, a cabinetry company operating north of Pittsburgh.
At family gatherings, Mom referred to him as **“an entrepreneur.”**
Banks referred to him differently.
His showroom in Wexford had been losing money for nearly a year.
He had six employees, an expensive leased truck, equipment financing, unpaid suppliers, business credit cards, and a commercial landlord who had stopped accepting promises as payment.
The company owed nearly **$148,000**.
Then Tyler’s lender offered a restructuring loan.
There was one condition.
He needed a guarantor with strong credit and reliable income.
Mom’s pension wasn’t enough.
Melissa worked part-time.
That left me.
Tyler took me to lunch at a steakhouse I knew he could not afford.
He ordered bourbon before noon.
“You’re not borrowing anything,” he told me. “It’s literally just your signature.”
I stared at him.
“A signature guaranteeing a loan.”
“Technically.”
“How much?”
He shifted in his seat.
“Anna.”
“How much, Tyler?”
“One seventy-five.”
I almost laughed.
“Thousand?”
He gave me a look suggesting I was being intentionally difficult.
“You know the company has assets.”
“Then the company can guarantee it.”
“The bank wants additional security.”
“Meaning me.”
“Meaning family.”
There it was.
The word used whenever someone wanted access to my money.
I asked him for his financial statements.
He became insulted.
I asked for tax returns.
He called me distrustful.
I asked for current debts.
He said I was acting like an auditor instead of a sister.
Eventually, after three days of arguing, he emailed me partial records.
I spent an entire Saturday reviewing them.
The numbers were worse than I expected.
Tyler’s business wasn’t suffering from one temporary problem.
It had **no stable cash-flow plan**.
Several large clients were more than ninety days overdue.
His margins had shrunk.
The showroom rent was absurd.
The truck lease belonged to a vehicle more appropriate for advertising success than earning revenue.
Two suppliers had put him on prepaid terms.
The refinancing loan would not rescue his company.
It would simply gather several fires into one larger fire and invite me to stand inside it.
So I said no.
I also offered him something else.
“I’ll pay for a meeting with a small-business restructuring accountant.”
Tyler leaned back in his chair.
“You think I need someone to tell me how to run my company?”
“I think you need someone who doesn’t care about your feelings.”
His face changed.
