

"Two hundred thousand dollars?" I repeated quietly, staring at the glossy photo of the $1.4 million brick mansion sitting between my coffee cup and the senior living brochures. "Daniel, you and Ashley don't have two hundred thousand dollars in liquid savings. Where did the earnest money deposit come from?"
Daniel couldn't even look me in the eye. He stared down at his trembling hands while Ashley crossed her arms, raising her chin defiantly.
"We unlocked your dead equity, Eleanor," Ashley said, her voice frighteningly calm. "Three weeks ago, my dad used his Massachusetts Notary Public commission to notarize a Durable Power of Attorney with your signature on it. We used that POA to open a $250,000 Home Equity Line of Credit against your house."
The room went completely silent. I looked at Ashley’s father, George—a man who had been a licensed notary and insurance adjuster for thirty years—and then at my son.
"You forged my signature on a Power of Attorney," I said, my voice barely above a whisper, "and took out a quarter-million-dollar mortgage on the home your father worked forty years to pay off?"
"It’s just a bridge loan, Mom!" Daniel pleaded, leaning across the table, his face shiny with sweat. "Listen to me! Two hundred grand went straight into the builder’s non-refundable escrow account for the new house, and we used the other fifty grand to pay off Ashley’s credit cards so our debt-to-income ratio would qualify for the main mortgage! Once your house sells in April for $980,000, the HELOC gets paid off automatically at closing, we use the rest of your equity for the down payment, and nobody ever knows the difference!"
"And what if I refuse to sell my house?" I asked coldly.
George leaned forward, his grandfatherly smile completely gone. "Think very carefully before you do anything rash, Eleanor. The closing date on the new property is in fourteen days. If you go to the bank or the police and claim that Power of Attorney was forged, the bank recalls the $250,000 immediately, they lose the $200,000 deposit, and the District Attorney puts your only son in state prison for felony bank fraud. Your grandchildren, Lucy and Ben, will grow up visiting their father behind glass. Is a four-bedroom house really worth destroying your own son’s life?"
Patricia patted my hand across the table with icy arrogance. "All you have to do is sign the listing agreement Lauren brought you, and sign a simple ratification form stating you authorized the loan. You move into a lovely one-bedroom senior apartment next month, and the family stays intact."
They had me cornered—or so they thought. They were counting on a seventy-two-year-old mother’s love to shield them from a crime that carried up to ten years in prison under Massachusetts elder financial abuse laws.
I looked around the table at the four of them. In that split second, I made my choice.
I let my shoulders slump, covered my face with both hands, and forced a shaky, defeated sob.
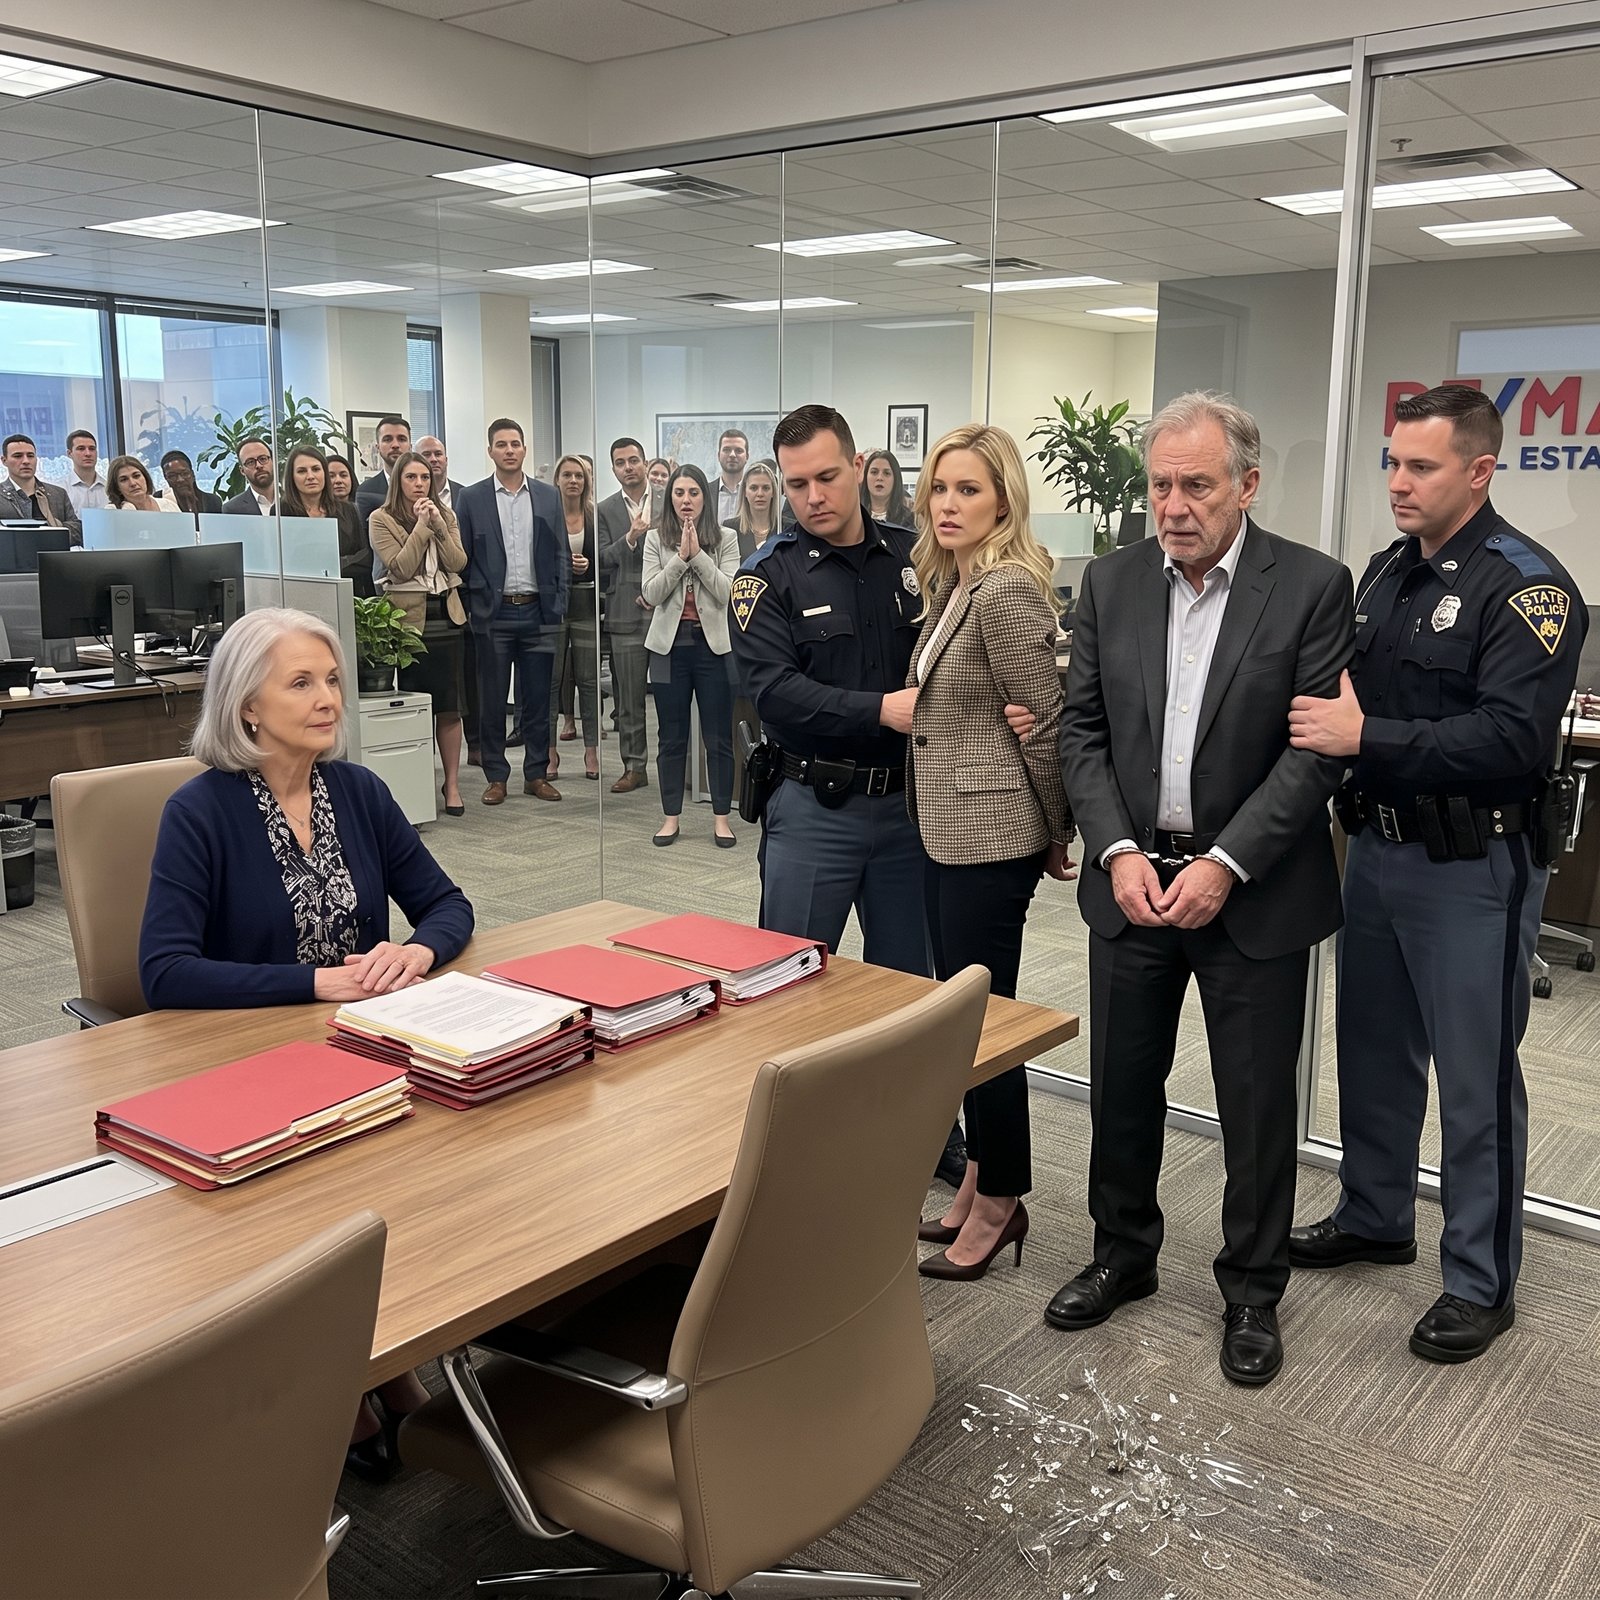
"I could never send Daniel to prison," I whispered through my fingers, watching Ashley and Patricia exchange a triumphant smirk out of the corner of my eye. "Give me until Wednesday. Robert left some municipal bonds linked to the house deed at my lawyer's office. Let me clear those out so there isn't a title delay. I’ll come down to Ashley’s brokerage office on Wednesday at 2:00 PM and sign the listing agreement and the ratification papers in front of her managing broker so everything is official."
Daniel let out a massive sigh of relief, walking over to kiss the top of my head. "Thank you, Mom. I knew you’d do the right thing for the family."
"Of course, sweetheart," I said softly, picking up my purse and walking out to my car. "A mother always does what’s best for her family."
